保育料を経費に!訴訟 Lawsuit to Recognize Childcare Fees as a Necessary Business Expense
#働き方
#Labor Rights
現在の寄付総額 Current Total Raised
1,024,500円 ¥ 1,024,500
目標金額 Target amount
3,000,000円 ¥ 3,000,000
サポーター Supporter
92 人 92 supporters
 寄付する
Donate Now


働く親は、就労時間を確保するために子どもを保育園に預けます。仕事をするために支払ったのですから、その保育料は必要経費に該当するはずです。けれど、現在の課税実務では、育児は収入を得ることと切り離された「家庭内の消費」であるとして、保育料は必要経費に当たらないとされています。共働きが一般化し、働き方の多様化が進み、国を挙げた少子化対策が叫ばれる今、保育料も必要経費として認定されることを求める訴訟です。 Working parents entrust their children to daycare centers to secure sufficient working hours. Since these fees are paid to enable them to work, they should qualify as necessary expenses. However, under current tax practices, childcare fees are not recognized as necessary expenses because they are treated as a “household expense” separate from earning income. With dual-income households becoming the norm, the diversification of work styles, and the national call for addressing the declining birthrate, this lawsuit seeks to have childcare fees officially recognized as necessary expenses.
第6回口頭弁論期日のご報告
Report on the 6th Oral Argument Hearing
2026/6/8 17:33
6月8日(月)11時30分より、東京地方裁判所703号法廷にて第6回口頭弁論期日が開かれました。日頃よりご支援いただいている皆さまに心より感謝申し上げます。
原告は、今回の期日に先立ち、税法学者である、三木義一青山学院大学教授、藤間大順神奈川大学准教授のお二人の意見書を提出し(三木教授意見書、藤間准教授意見書)、その内容を敷衍して第4準備書面として主張しました。また、第5準備書面において各原告の個別事情に関して追完した証拠の説明を行いました。前者の主張に関する概要は以下のとおりです。
① 国は「仕事との直接の関係」が必要だと主張している
国は、保育料は育児のための支出であり、事業活動と「直接」関係していないとして、必要経費に当たらないと主張しています。しかし、所得税法の条文には「直接」という文言はありません。今回提出した意見書では、「直接関連性」という要件は法律に書かれていないことが改めて指摘されています。法律にない要件を後から付け加えて経費を認めないことは、租税法律主義にも反するというのが私たちの主張です。
② 税法の本来の考え方は「一般対応経費は広く認める」ことにある
今回の書面では、現行所得税法が作られた1960年代の税制調査会答申や立法資料も詳しく取り上げました。そこでは、所得を得ることに直接寄与した費用だけでなく、事業に関係する費用はできるだけ広く経費として認めるべきという考え方が示されています。現在の実務は法律の文言以上に必要経費の範囲を狭く解釈していると指摘されています。
今回の裁判は、「必要経費とは何か」という税法の基本原則そのものが問われています。
③ 保育料は「育児だから経費にならない」では判断できない
国は、保育料は育児費用だから家事費であると主張しています。しかし私たちは、育児という言葉だけで経費性を否定することはできないと反論しています。例えば、なぜその支出をしたのかどのような仕事をしているのかその支出によって収入を得られたのかといった具体的事情を見なければ、本当に仕事と関係があるかは判断できません。意見書においても、支出の性質や目的、効果を総合的に判断すべきとしています。
④ 認可保育園はそもそも「就労のため」の制度
認可保育園に入園するためには、就労証明書就労状況申告書などを自治体に提出し、「保育の必要性」の認定を受ける必要があります。つまり認可保育園の保育料は、親が働くことを前提として発生する費用です。子どもを家庭で保育しているだけでは「保育料」は発生しません。その意味で、保育料は仕事をするために生じる費用であり、単なる家事費ではないというのが今回の意見書の重要な指摘です。
今回提出した書面で私たちが裁判所に伝えたかったことはシンプルです。
「育児だから経費にならない」という抽象論ではなく、実際にその支出がどのような目的で行われ、どのような役割を果たしているのかを見て判断してほしい。税法の条文、立法趣旨、近年の裁判例、そして2名の税法学者の意見書はいずれも、この考え方を支持しています。
また、今回の期日では、三木先生・藤間先生と原告お二人の人証請求を行い(証拠申出書)、このうち、原告2名の尋問の実施が決定されました。次回は、原告2人に対する尋問を行う運びとなりました。9月以降の日程で調整中ですので、分かり次第お知らせいたします。
次回期日
日時:9月以降(未定)
場所:東京地方裁判所(法廷は未定)
ぜひお誘い合わせのうえ、傍聴にお越しください。
引き続きのご支援をどうぞよろしくお願いいたします。
The sixth oral argument hearing was held on Monday, June 8th, at 11:30 AM in Courtroom 703 of the Tokyo District Court. We express our sincere gratitude to everyone who has supported us on a regular basis.
Prior to this hearing, the plaintiffs submitted opinion papers from two tax law scholars, Professor Yoshikazu Miki of Aoyama Gakuin University and Associate Professor Daijun Fujima of Kanagawa University ( Professor Miki's opinion paper , Associate Professor Fujima's opinion paper ), and elaborated on their contents in their fourth preparatory document . Furthermore, in their fifth preparatory document, they explained the supplementary evidence regarding the individual circumstances of each plaintiff. The summary of the former arguments is as follows:
① The government is claiming that a "direct connection to work" is necessary.
The government argues that childcare fees are expenses for childcare and not "directly" related to business activities, and therefore do not qualify as necessary expenses. However, the word "directly" is not used in the Income Tax Act. In the opinion paper we have submitted, we reiterate that the requirement of "direct relevance" is not written in the law. Our argument is that adding a requirement that is not in the law afterward to deny the recognition of expenses violates the principle of legality in taxation.
② The fundamental principle of tax law is to "broadly recognize general expenses."
This document also examines in detail the reports and legislative materials from the Tax System Research Council in the 1960s, when the current Income Tax Law was created. These materials indicate that expenses should be recognized as broadly as possible, encompassing not only those directly contributing to income generation, but also those related to the business. It has been pointed out that current practice interprets the scope of necessary expenses more narrowly than the legal wording.
This trial is at stake because it questions the very fundamental principle of tax law: "What constitutes a necessary expense?"
③ Childcare fees cannot be judged on the basis of "it's childcare, so it's not a business expense."
The government argues that childcare fees are childcare expenses and therefore household expenses. However, we counter that the mere term "childcare" cannot negate their business expense status. For example, without examining specific circumstances such as why the expenditure was made, what kind of work is involved, and whether income was generated from the expenditure, it is impossible to determine whether it is truly related to work. Our opinion paper also states that the nature, purpose, and effect of the expenditure should be judged comprehensively.
④ Licensed daycare centers are fundamentally a system "for the purpose of employment."
To enroll a child in a licensed daycare center, parents must submit documents such as an employment certificate and a declaration of employment status to the local government and receive certification of the "need for childcare." In other words, the childcare fees for licensed daycare centers are expenses incurred on the premise that parents are working. No "childcare fees" are incurred if the child is simply cared for at home. In that sense, a key point of this opinion paper is that childcare fees are expenses incurred in order to work, and not simply household expenses.
What we wanted to convey to the court in the document we submitted this time was simple.
Instead of making the abstract argument that "it's not a business expense because it's for childcare," I want you to look at the actual purpose and role of the expenditure before making a judgment. The provisions of the tax law, the legislative intent, recent court cases, and the opinions of two tax law scholars all support this viewpoint.
Furthermore, at this hearing, we requested testimony from Professor Miki, Professor Fujima, and the two plaintiffs ( submission of evidence ), and it was decided that the two plaintiffs would be questioned . The next hearing will be to question the two plaintiffs. We are currently coordinating the date for September or later, and will inform you as soon as it is decided.
Next due date <br data-start="489" data-end="492">Date and time: September or later (undecided)
Location: Tokyo District Court (Courtroom to be determined)
Please feel free to invite others and come observe the proceedings.
We would greatly appreciate your continued support.
第5回期日報告
5th Daily Report
2026/4/23 22:07
4月23日(木)15時00分より、東京地方裁判所703号法廷にて第5回口頭弁論期日が開かれました。日頃よりご支援いただいている皆さまに心より感謝申し上げます。
原告は、今回の期日に先立ち第3準備書面を提出し、主に以下の点について反論及び主張を補充しました。
1.「直接関連性」要件は不要
被告は、必要経費といえるためには業務との「直接」関連性が必要と主張するが、これは所得税法37条の文理に反し、租税法律主義にも反する。裁判例上も「直接」関連性は独立の要件として確立しておらず、必要経費該当性は、支出の性質・目的・効果等を踏まえた総合判断によるべきである。
2.保育料は家事費ではない
被告は、保育料のように育児にかかる支出は「本質的に個人消費」と位置付けるが、支出の分類のみで必要経費性を否定するのは誤りである。
3.保育料は業務に関連する支出である
必要経費は業務そのものに直結する支出に限られず、就労の前提条件を整える費用としても業務関連性が認められる。本件保育料は必要経費に該当する。
4.今日における保育所の性質・社会的位置づけ(就労支援機能)
保育所は歴史的・制度的に、親の就労を支える機能を強めてきており、保育料を専ら「子どものための支出」と評価する前提自体が誤っている。
次回期日では、原告側が、税法研究者2名の専門家意見書を提出予定です。
次回期日
6月8日(月)11時30分~
東京地方裁判所703号法廷
ぜひお誘い合わせのうえ、傍聴にお越しください。
引き続きのご支援をどうぞよろしくお願いいたします。
The fifth oral argument hearing was held on Thursday, April 23rd, at 3:00 PM in Courtroom 703 of the Tokyo District Court. We express our sincere gratitude to everyone who has supported us on a regular basis.
Prior to this hearing, the plaintiff submitted preparatory brief (3) and argued the following:
In preparatory brief (3), we refuted and supplemented the defendant's claims, mainly focusing on the following points.
1. The "direct relevance" requirement is unnecessary. The defendant argues that a "direct" relevance to the business is necessary for an expense to qualify as a necessary expense, but this contradicts the wording of Article 37 of the Income Tax Act and the principle of legality in taxation. Court precedents do not establish "direct relevance" as an independent requirement, and the qualification of an expense as a necessary expense should be determined by a comprehensive judgment that takes into account the nature, purpose, and effect of the expenditure.
2. Childcare fees are not household expenses. The defendant argues that expenses related to childcare, such as childcare fees, are "essentially personal consumption," but it is wrong to deny their necessity based solely on the classification of expenses.
3. Childcare fees are considered business-related expenses . Business-related expenses are not limited to expenses directly related to the work itself, but also include expenses that prepare the prerequisites for employment. In this case, the childcare fees qualify as business-related expenses.
4. The nature and social position of childcare centers today (employment support function)
Historically and institutionally, daycare centers have increasingly served to support parents' employment, and the premise that daycare fees are solely "expenses for the child" is fundamentally flawed.
At the next hearing, the plaintiffs plan to submit expert opinions from two tax law researchers.
Next due date
June 8th (Monday) 11:30am~
Tokyo District Court, Courtroom 703
Please feel free to invite others and come observe the proceedings.
We would greatly appreciate your continued support.
第4回期日報告
4th Periodic Report
2026/2/24 16:52
2月24日(火)13時30分より、東京地方裁判所703号法廷にて第4回口頭弁論期日が開かれました。日頃よりご支援いただいている皆さまに心より感謝申し上げます。
被告は、今回の期日に先立ち訴状に対する反論書面を提出し次のように主張しました。
※国の主張の詳細はこちら(準備書面⑵)でご覧いただけます。
1 必要経費の判断枠組みについて
被告は、必要経費に該当するためには当該支出が特定の経済活動と直接的に結びついていること(いわゆる「直接関連性」)が必要であると主張しました。必要経費(所得税法37条1項)の法解釈上、「直接」要件の有無が争点となっています。
2 保育所の性質から保育料は必要経費に当たらない
被告は、保育所は一貫して「子の養護・教育のための施設」(児童福祉法39条)であり、その性質は制度開始以来変更されていないと主張しています。さらに被告は、保育所を利用することによって親が勤務時間を確保できる点についても、それは「保護者が第一義的責任を負う」という法制度のもとで育児責任を果たすための社会的支援に伴う副次的効果にすぎない。したがって、必要経費とはなり得ないと主張しました。今日の保育所制度の性質が「子どものためか」「親の就労のためか」どちらの性質が強いかが争点となっています。
次回期日では、今回提出された被告側書面に対し、原告側から反論を行いその内容について口頭で陳述を行う予定です。
次回期日
4月23日(木)15時~
東京地方裁判所703号法廷
ぜひお誘い合わせのうえ、傍聴にお越しください。
引き続きのご支援をどうぞよろしくお願いいたします。
The fourth oral argument hearing was held on Tuesday, February 24th at 1:30 PM in Courtroom 703 of the Tokyo District Court. We would like to express our sincere gratitude to everyone who has continued to support us.
Prior to this hearing, the defendants filed a statement of their objections to the complaint, arguing as follows:
*For details of the government's argument, please see here ( Preparatory Document ⑵ ) to view it.
Regarding the framework for determining necessary expenses , the defendant argued that in order for an expense to be considered a necessary expense, it must be directly linked to a specific economic activity (so-called "direct connection"). The issue at issue is whether or not the "direct" requirement exists in the legal interpretation of necessary expenses (Article 37, Paragraph 1 of the Income Tax Act).
2. Given the nature of daycare centers, daycare fees are not considered necessary expenses. The defendants argue that daycare centers have always been "facilities for the care and education of children" (Article 39 of the Child Welfare Act), and that this nature has not changed since the system was established. Furthermore, the defendants argued that the fact that daycare centers allow parents to secure working hours is merely a secondary benefit of social support for fulfilling childcare responsibilities under a legal system that "bears primary responsibility for parents." Therefore, they cannot be considered necessary expenses. The issue at issue is whether the nature of today's daycare center system is "for the children" or "for the parents' working lives."
At the next hearing, the plaintiff will refute the defendant's written submissions and make an oral statement regarding the contents of the rebuttal.
Next date
April 23rd (Thursday) 3pm
Tokyo District Court, Courtroom 703
Please invite your friends and come to observe the hearing.
We appreciate your continued support.
第3回期日報告
Third Daily Report
2025/11/18 16:40
11月18日(火)11時00より、東京地方裁判所703号法廷にて第3回口頭弁論期日が開かれました。日頃よりご支援いただいている皆さまに心より感謝申し上げます。
被告の主張概要
前回の期日で被告は、大要、
「保育園の主たる目的は子どもの養護・教育(子の福祉)である」
「保育料はその対価であり、親の就労時間の確保はあくまで副次的な効果にすぎない」
「したがって、保育料の支出は所得稼得とは関係がなく必要経費には当たらない」
との論理に基づいて必要経費性を否定する立場を示しました(準備書面⑴)。
原告の主張概要
今回の期日では、主に上記の国の主張に対する反論を行いました。
まず、必要経費(所得税法37条1項)に当たるか否かの判断枠組みについて、従来の裁判例・学説に加え、近時の裁判例も分析したうえで、判断枠組みを整理して提示しました(第1準備書面【必要経費該当性判断枠組み及び保育料の該当性について】 )。
そのうえで、今日の保育所の中心的な役割は「親の就労を支えること」であるという点から、被告の主張の誤りを指摘しました(第2準備書面【今日における保育所利用の目的】 )。その概要は以下のとおりです。
かつて、保育所は子どもの養護教育のための施設だったが、この30年間で保育所の性質は大きく転換。現在保育所は働く親を支えるための施設として制度的に位置づけられている。
この転換を示す主要な制度改革
① 1997年児童福祉法改正:保育所は「救済中心」から、保護者が自由に選択する「サービス」へ転換。
② 2012年児童福祉法改正:利用要件が「保育に欠ける」→「保育を必要とする」へ改められ、働きたい親が誰でも利用 できる仕組みへ。その他政府の政策
・2016年、「保育園落ちた日本死ね!」発言を受け、安倍首相が「待機児童ゼロを必ず実現する決意」と宣言
・2020年、緊急事態宣言下で、医療従事者が勤務を継続できるよう自治体に子の預かりを徹底要請現在、保育所利用の96%は就労が理由。
→今日の保育所が就労支援施設であることは明白。
また、期日では、江夏代理人が「必要経費の判断枠組み」について、戸田代理人が「保育所の性質」について、それぞれプレゼンテーションを行いました(江夏代理人陳述原稿・投影資料、戸田代理人陳述原稿・投影資料)
期日後には、傍聴にお越しいただいた方々に被告の主張内容について簡単な解説を行い充実した時間となりました。

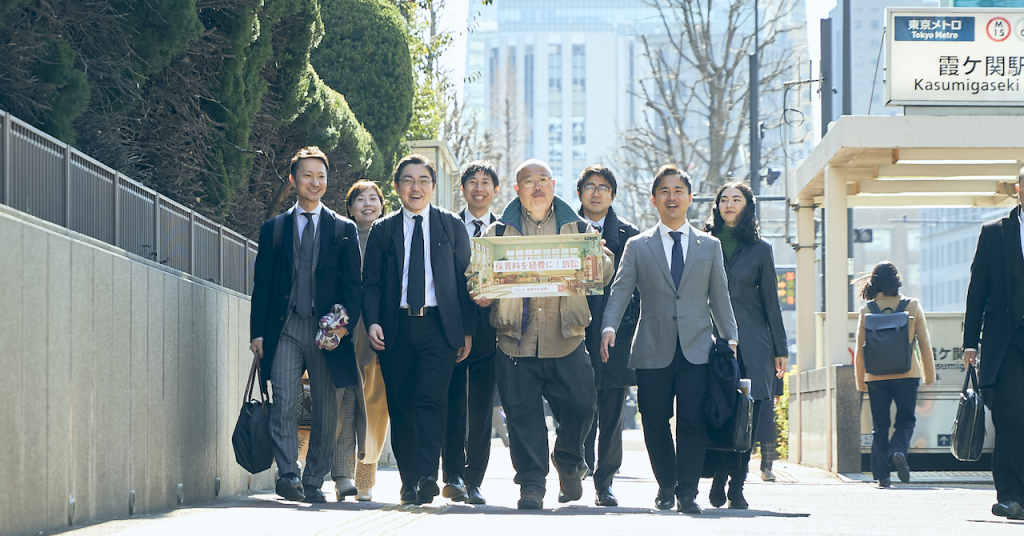
▲期日後、東京地裁の外で原告・弁護団の皆さまと
次回期日
次回期日では、今回提出された原告側書面に対し、被告側が反論を行う予定です(被告の書面提出締切は2月17日)。
2026年2月24日(火)13時30分~
東京地方裁判所703号法廷
ぜひお誘い合わせのうえ、傍聴にお越しください。
引き続きのご支援をどうぞよろしくお願いいたします。
The third oral argument hearing was held on Tuesday, November 18th at 11:00 a.m. in Courtroom 703 of the Tokyo District Court. We would like to express our sincere gratitude to everyone who has continued to support us.
Summary of Defendant's Argument <br>At the previous hearing, the defendant argued, in summary:
"The main purpose of a nursery school is to care for and educate children (child welfare)."
"Childcare fees are the price to pay, and securing working hours for parents is merely a secondary benefit."
"Therefore, childcare fees are not related to income earning and are not considered necessary expenses."
Based on this logic, they took the position that it was not a necessary expense ( Preparatory document ⑴ ).
Summary of Plaintiff's Arguments
At this hearing, we mainly refuted the claims of the above countries.
First, we analyzed recent court cases as well as existing court cases and academic theories to determine whether an expense constitutes a necessary expense ( Article 37, Paragraph 1 of the Income Tax Act), and then organized and presented the framework for determining whether an expense constitutes a necessary expense (First Preparatory Document [Regarding the framework for determining whether an expense constitutes a necessary expense and the applicability of childcare fees] ).
Based on this, the court pointed out the error in the defendant's argument, stating that the central role of childcare centers today is to "support parents in their employment" (Preparatory Brief No. 2 [Purpose of Childcare Center Use Today] ). The summary is as follows:
In the past, nurseries were facilities for providing special education for children, but over the past 30 years, the nature of nurseries has changed dramatically. Now, nurseries are institutionally positioned as facilities to support working parents.
Major institutional reforms that indicate this shift: 1. 1997 amendment to the Child Welfare Act: Daycare centers changed from being "relief-centered" to being "services" that parents could freely choose.
② 2012 Amendment to the Child Welfare Act: The eligibility criteria were changed from “lacking childcare” to “needing childcare,” making the system accessible to all parents who want to work.Other government policies: In 2016, Prime Minister Abe declared, "We are determined to achieve zero waiting lists for childcare," following his comment, "Japan, die! I couldn't get into daycare!" In 2020, under the state of emergency, he made a thorough request to local governments to provide childcare so that medical workers could continue working.
Currently, 96% of daycare center use is due to work.
→It is clear that today's daycare centers are employment support facilities.
At the hearing, attorney Enatsu gave a presentation on the "framework for determining necessary expenses," and attorney Toda gave a presentation on the "nature of daycare centers." ( Enatsu's statement and projected materials , Toda's statement and projected materials )
After the hearing, a brief explanation of the defendant's claims was given to those in attendance, making for a very productive session.
After the hearing, with the plaintiffs and their lawyers outside the Tokyo District Court
Next date
At the next hearing, the defendant is scheduled to refute the plaintiff's written rebuttal (the deadline for the defendant to submit written rebuttals is February 17th).
February 24, 2026 (Tuesday) 13:30~
Tokyo District Court, Courtroom 703
Please invite your friends and come to observe the hearing.
We appreciate your continued support.
第2回期日報告
2nd Period Daily Report
2025/9/2 16:58
9月2日(火)13時30分より、東京地方裁判所703号法廷にて第2回口頭弁論期日が開かれました。日頃よりご支援いただいている皆さまに心より感謝申し上げます。
被告は、今回の期日に先立ち訴状に対する反論書面を提出し、「保育は福祉であり保育料はその対価である」との論理に基づいて必要経費性を否定する主張を展開しました。※国の主張の詳細はこちら(準備書面⑴)でご覧いただけます。
期日後には、傍聴にお越しいただいた方々に被告の主張内容について簡単な解説を行い充実した時間となりました。

▲期日後、傍聴に来られた皆さまと
次回期日では、今回提出された被告側書面に対し、原告側から反論を行いその内容について口頭でのプレゼンテーションを行う予定です。
次回期日
11月18日(火)11時~
東京地方裁判所703号法廷
ぜひお誘い合わせのうえ、傍聴にお越しください。
引き続きのご支援をどうぞよろしくお願いいたします。
The second oral argument hearing was held on Tuesday, September 2nd at 1:30 PM in Courtroom 703 of the Tokyo District Court. We would like to express our sincere gratitude to everyone who has continued to support us.
Prior to this hearing, the defendant submitted a written rebuttal to the complaint, arguing that childcare is a form of welfare and that childcare fees are compensation for it, denying that the expenses are necessary expenses. You can see it in the preparatory documents (⑴ ).
After the hearing, a brief explanation of the defendant's claims was given to those in attendance, making for a very productive session.
▲After the hearing, with everyone who came to observe
At the next hearing, the plaintiffs will refute the defendants' written submissions and make an oral presentation on the contents of their rebuttals.
Next date
Tuesday, November 18th from 11am
Tokyo District Court, Courtroom 703
Please invite your friends and come to observe the hearing.
We appreciate your continued support.
第1回期日報告
1st Periodic Report
2025/6/5 15:50
本日(2025年6月5日)午前10時30分より、東京地方裁判所703号法廷にて、本件の第1回口頭弁論が開かれました。
法廷では、原告側が訴状(要約版)を、被告国が答弁書をそれぞれ陳述しました。
その後、原告の松村さん、倉持さん、そして代理人の戸田弁護士がそれぞれ意見陳述・訴状陳述を行いました。
当日のスピーチの内容については、以下よりご覧いただけます。
(※リンク:松村さん、倉持さん、戸田弁護士)
裁判所は、被告・国に対して、次回期日までに反論書面を提出するよう指示し、その期限は7月31日とされました。
期日後には、期日報告会を開催し、裁判の概要や今後の見通しについての解説を行いました。いずれも多くの方にご参加いただき活発な議論が交わされました。
次回期日は【9月2日午後13時30分】より、引き続き東京地方裁判所703号法廷で行われます。
ぜひ次回もご傍聴・ご参加いただければ幸いです。引き続き、皆さまのご支援をよろしくお願い申し上げます。

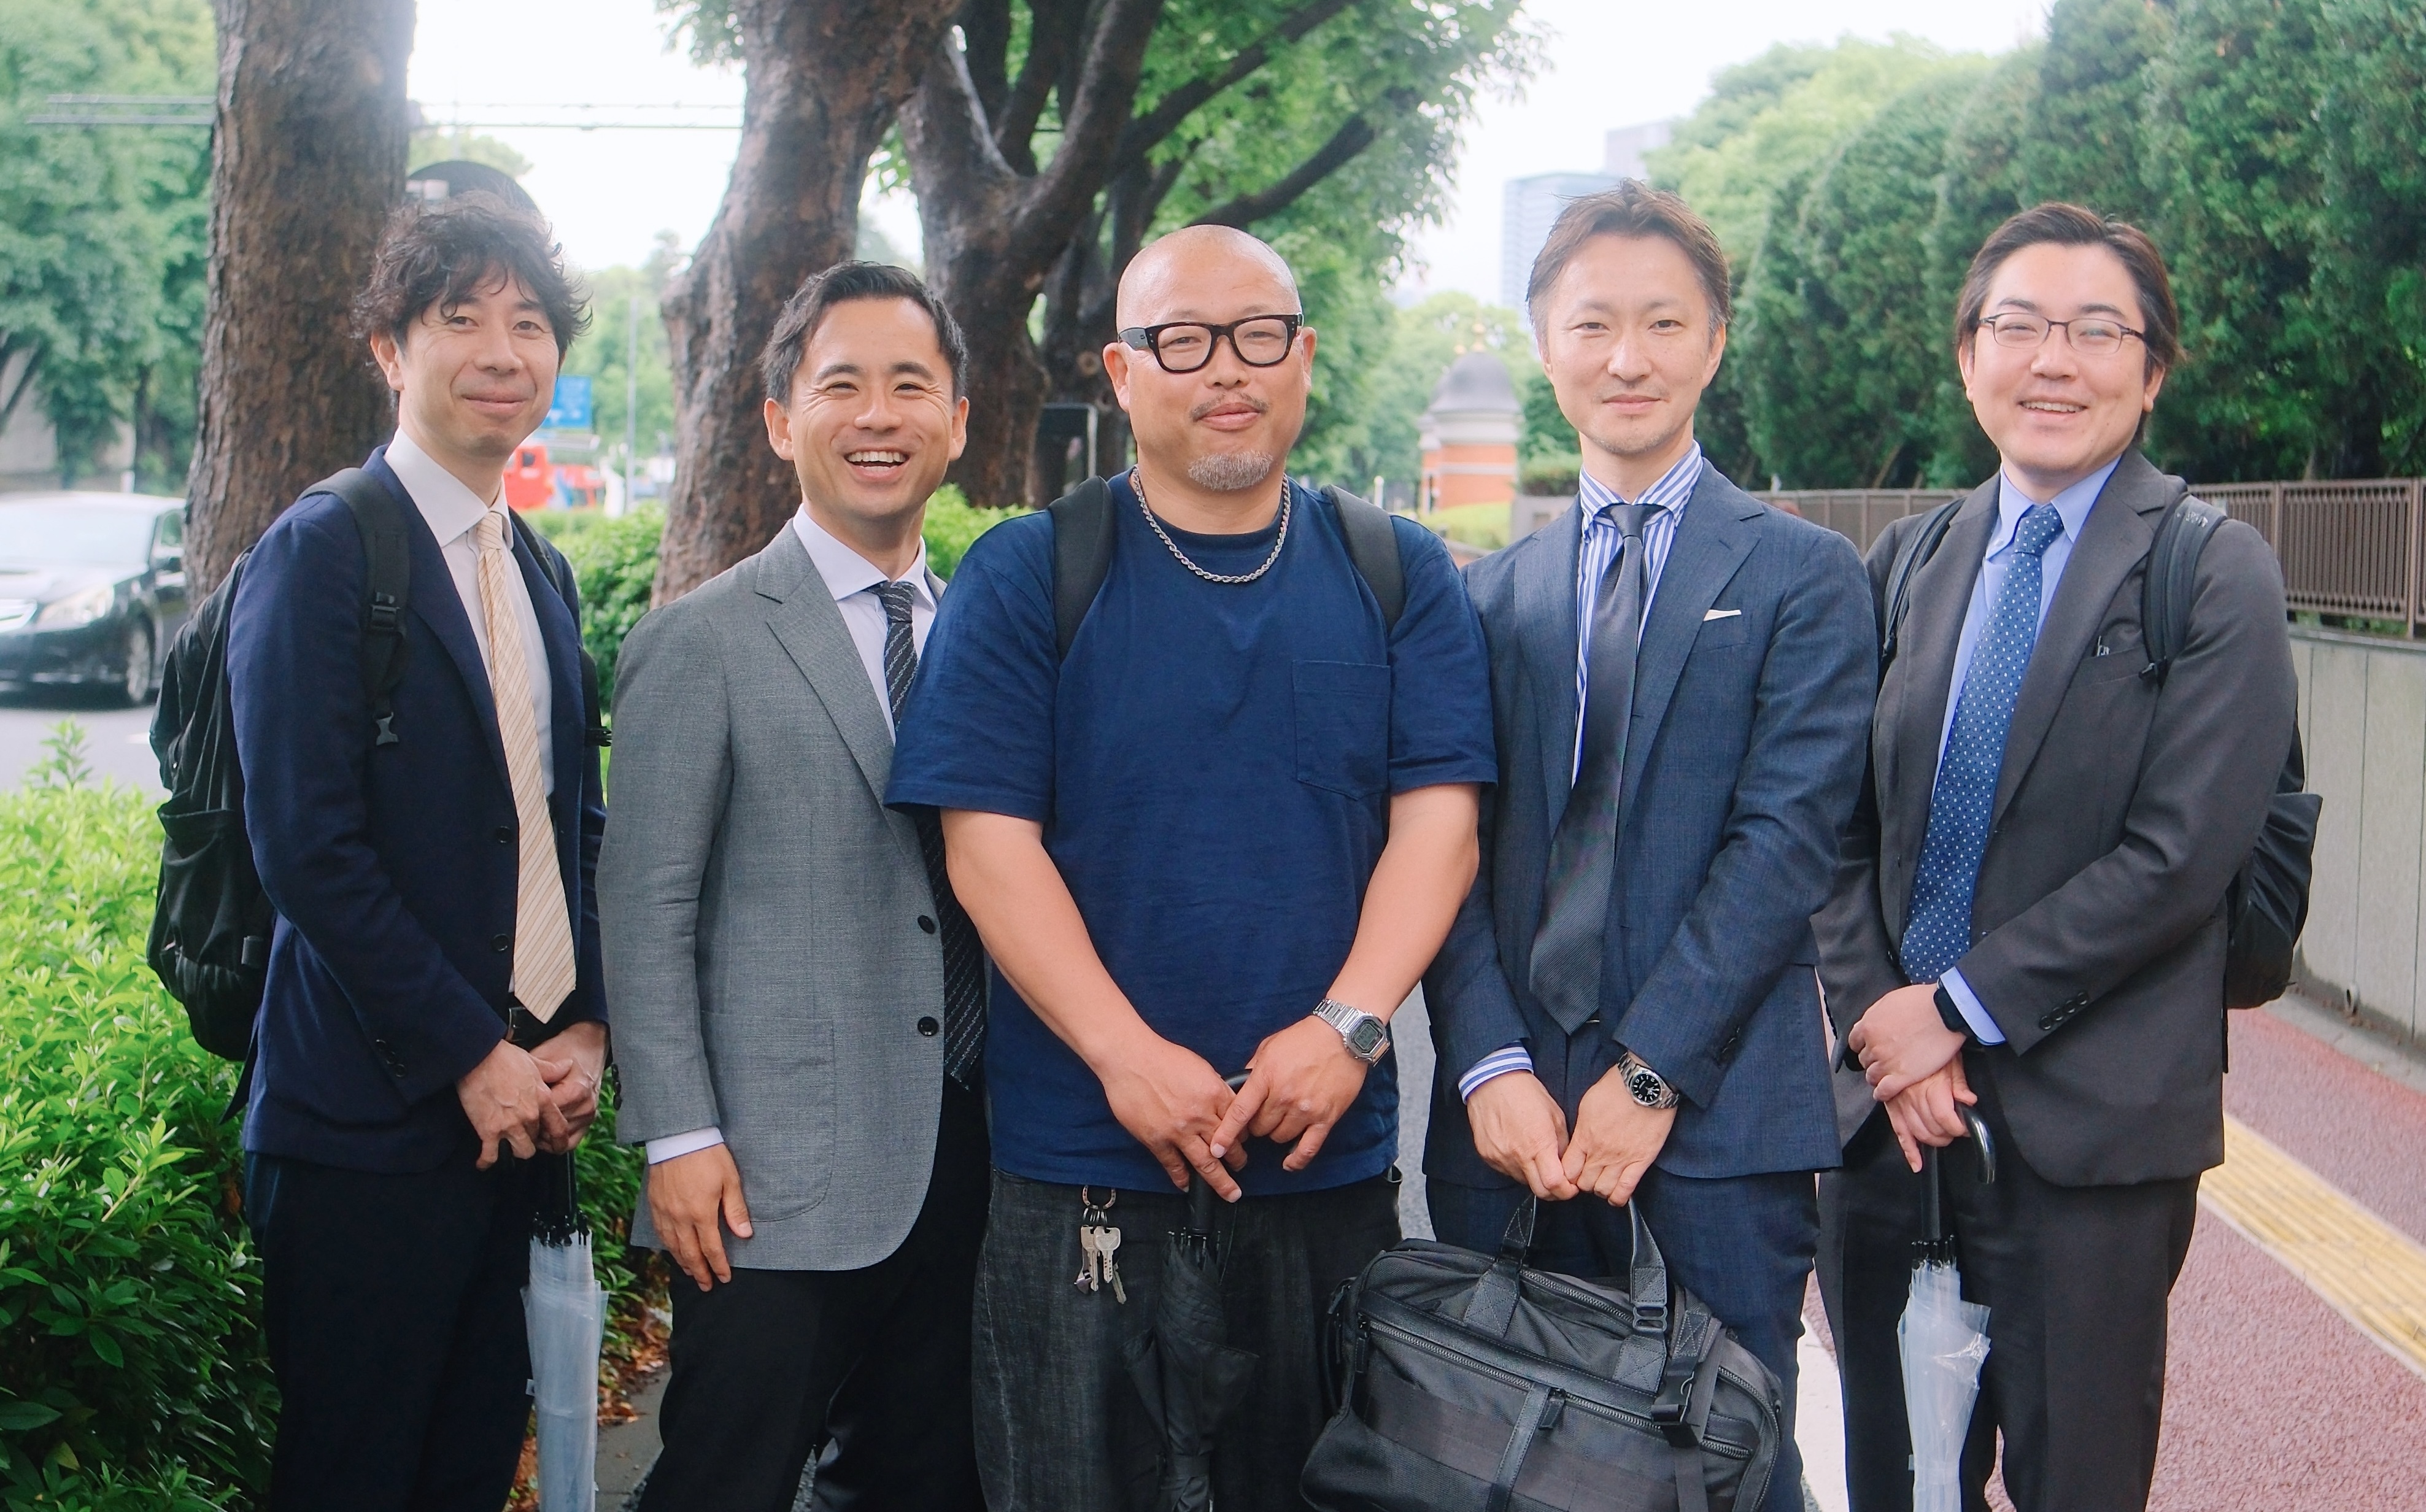
▲裁判所前で原告・弁護団と

▲期日報告会に参加した皆さんと
The first oral argument for this case was held today (June 5, 2025) at 10:30 a.m. in Courtroom 703 of the Tokyo District Court.
In court, the plaintiffs presented a summary of their complaint , and the defendants presented their answer .
Afterwards, the plaintiffs, Mr. Matsumura and Mr. Kuramochi, and their attorney, Mr. Toda, each made statements of opinion and presented their complaint.
Please see below for details of the speeches given on the day.
(※Link: Mr. Matsumura , Mr. Kuramochi , Attorney Toda )
The court instructed the defendant/government to submit a written rebuttal by the next hearing, which is set for July 31.
After the hearing, we held a hearing report session to provide an overview of the trial and future prospects. Many people attended both sessions and lively discussions were held.
The next hearing will be held on September 2nd at 1:30 pm in Courtroom 703 of the Tokyo District Court.
We hope you will attend and participate in our next meeting as well. Thank you for your continued support.
▲With the plaintiffs and their lawyers in front of the court
▲With everyone who participated in the deadline report meeting
提訴会見レポートが掲載されました
The lawsuit conference report has been published
2025/2/27 16:00
2月25日に行った提訴会見について、CALL4が提訴会見レポートを作成してくださり、本日掲載されました。
ぜひご覧ください。
提訴会見レポート「保育料を経費に!訴訟」- 2025年2月25日@司法記者クラブ
CALL4 prepared a report on the lawsuit press conference held on February 25th, which was published today.
Please take a look.
【提訴ご報告】保険料を経費に!訴訟
[Lawsuit Report] Insurance premiums as expenses! Lawsuit
2025/2/26 11:50
「保育料を経費に!訴訟」をご支援いただき、ご支援ありがとうございます。
今週2/25(火)「保育料を経費に!訴訟」を東京地裁に提訴したことをご報告いたします。
同日14時より司法記者クラブにて会見を行いました。

会見では江夏弁護士、戸田弁護士より訴訟の概要や本訴訟の法的意義についてご説明しました。
戸田弁護士は、今回の訴訟は、必要経費とは何か家事費とは何かを問いなおす「法的な意義」を持つことを強調しました。
必要経費は業務に直接つながるものだけという(税務署が現在採用している)定義は、必要経費を狭く捉えすぎなのではないかと指摘しました。
そもそも、高裁では事業と必ずしも「直接」関係がある支出でなくても、関連性があれば直接経費必要経費に認められるという判決がでています。
それなのに関わらず、税務署は変わらず直接性にこだわり、今も保育料をあくまでも家事費と運用上捉えています。
そもそも保育料を家事費、つまり、「個人の消費生活上の支出」とする運用は男性が外で稼ぎ、女性が無償で家事や育児を担う仮定モデルにも支えられています。
現在日本では共働きが7割に到達しています。
税務署の保育料を必要経費ではなく家事費という捉え方は、多様な働き方と保育のバランスをまもるためにも是正すべきです。
そのため、保育料が必要経費に当たることと同時に、家事費には当たらないとはっきりさせることが重要です。
会見には原告の一人である倉持さんも出席しました。倉持さんは、「子育ては大変だけど楽しい。だからこそ他の人々もチャレンジできるきっかけになりたかった。」と、おっしゃっていました。
司法を通じて、「必要経費」「家事費」の解釈に決着がつくことで保育料が経費で控除される社会を目指します。
引き続きご支援のほど、よろしくお願いいたします。


Thank you for your support of the "Make Childcare Fees an Expense! Lawsuit" campaign.
We are pleased to announce that this week on Tuesday, February 25th, we have filed a lawsuit in the Tokyo District Court entitled "Turn Childcare Fees into an Expense!"
A press conference was held at the Judicial Press Club at 2:00 p.m. on the same day.

At the press conference, attorneysEnatsu and Toda explained the details of the lawsuit and its legal significance.
Attorney Toda emphasized that this lawsuit has "legal significance" in that it raises new questions about what constitutes as necessary expenses and what constitutes as household expenses.
He also pointed out that the definition currently adopted by the tax office, which states that necessary expenses are only those directly related to business operations, is an overly narrow interpretation of necessary expenses.
In the first place, the High Court has ruled that even if an expenditure is not directly related to the business, it can be recognized as a necessary direct expense if there is a connection.
Despite this, the tax office still requires for a direct connection between business and expenses for it to be deemed as necessary expenses and therefore, still treats childcare fees as merely a household expense.
The attorneys also noted that another reason for the tax office not changing their decision in viewing the treatment of childcare fees as household expenses, or personal consumer expenditure, is due to the still ingrained misogynistic belief that men earn money outside the home and women take on the housework and childcare duties unpaid.
Yet, currently in Japan, 70% of households have dual incomes.
The tax office's view of childcare fees as household expenses rather than necessary expenses should be corrected in order to maintain a balance between diverse working styles and childcare.
Therefore, it is important to clarify that childcare fees are necessary expenses and not household expenses.
One of the plaintiffs, Mr. Kuramochi, also attended the press conference. He mentioned, "Raising children is hard, but fun. That's why I wanted to be an opportunity for other people to take on the challenge."
Through the judicial system, we aim to settle the interpretation of "necessary expenses" and "household expenses" so that childcare fees can be deducted as expenses.
We appreciate your continued support.


8 件中 1-8 件
1-8 of 8 cases
- 1
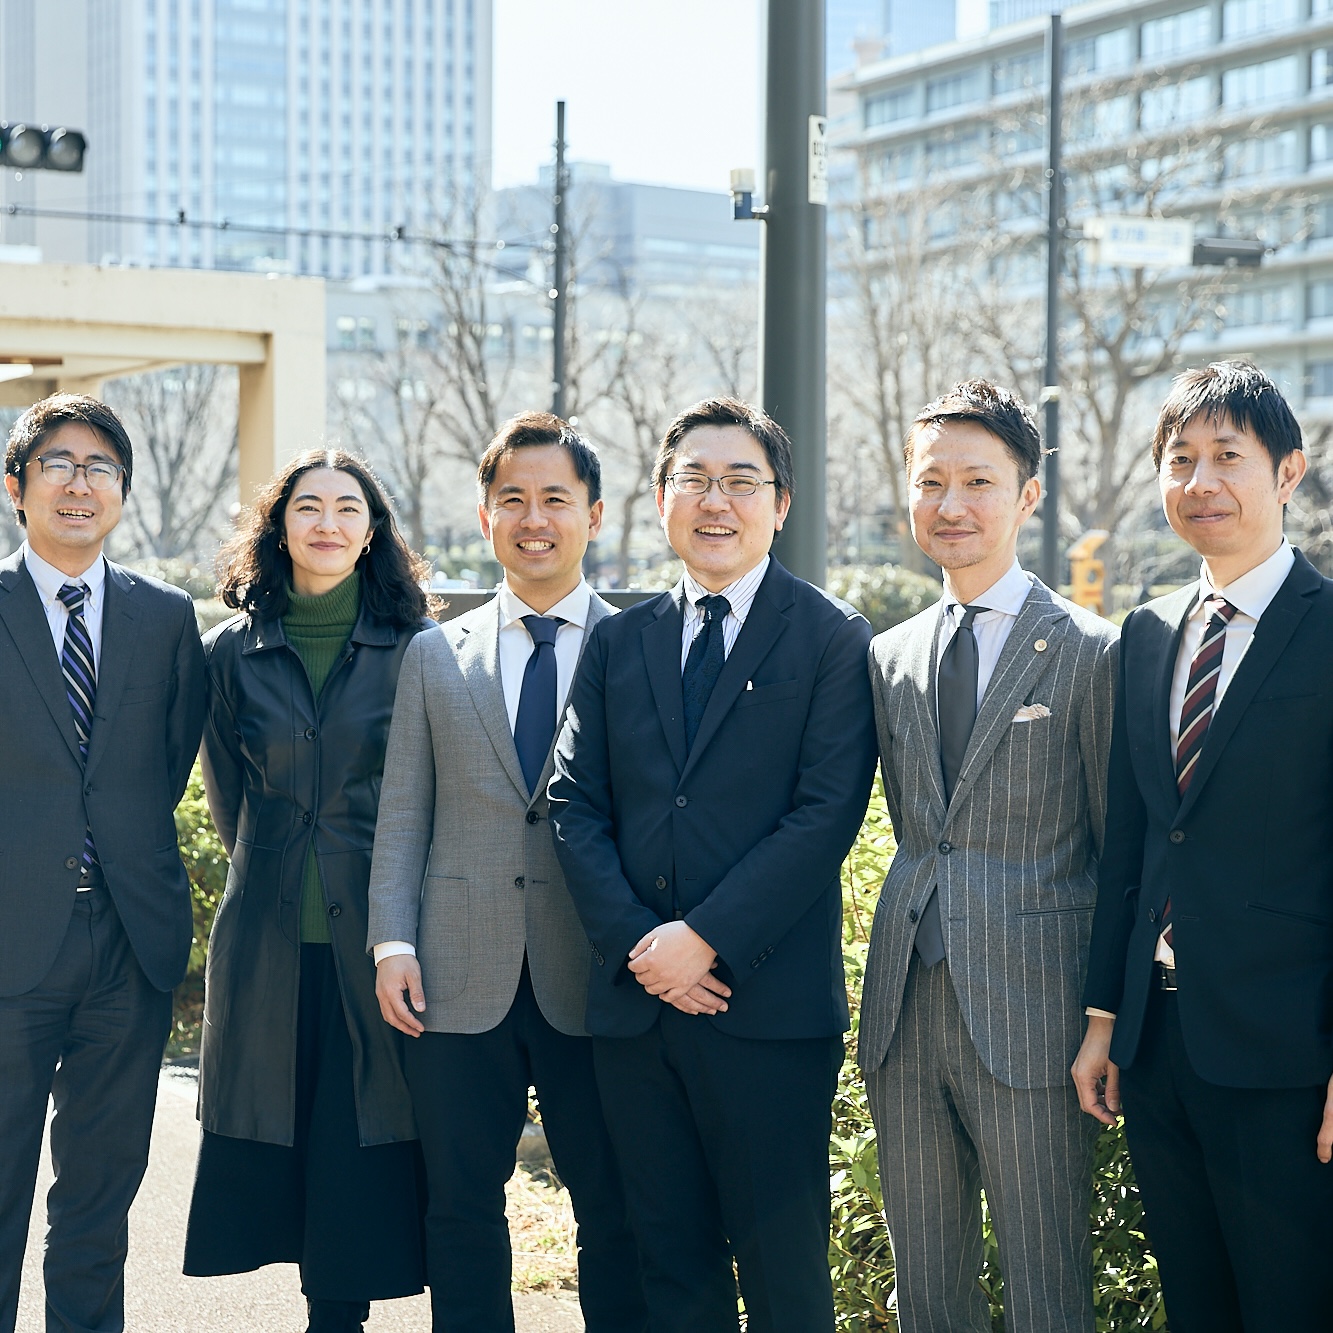
保育料を経費に!訴訟弁護団
「保育料を経費に!訴訟」の弁護団です
〈連絡先〉
「保育料を経費に!訴訟」代理人/東京法律事務所 所属
弁護士 江夏 大樹
Email: enatsu@tokyolaw.gr.jp
〈連絡先〉
「保育料を経費に!訴訟」代理人/東京法律事務所 所属
弁護士 江夏 大樹
Email: enatsu@tokyolaw.gr.jp
関連コラム
-
2025. 8. 31
-
2025. 2. 27